Best Health Insurance
To see the best health insurance plans, start by providing a few details about yourself:
RT Health Insurance 🏆 2026
5.0Award Winning, Affordable, Not-For-Profit Health Insurance.

Teachers Health Fund 🏆 2026

- See all


I spoke with J to get information about what benefits I could receive from Teachers Health Fund. he was pleasant and friendly and apart from the info… Read more
I asked for, he kindly offered me extra info which I didn't know about. How nice was it not to feel pushed off quickly or feel frustrated seeking details! Quite made my day... thank you J!! I was left with a good feeling and I wish you well in your job - you do it so well!
RT Health 🏆 2026


- See all

christina was very friendly, helpful and was easy to understanding her conversations. very prompt and thorough with her work. thank u. Show details

AIA Health Insurance 🏆 2026

- See all


Fast and easy processing of application. Accessible website and user friendly. Show details

Phoenix Health Fund
Adam called back at a time that suited me and was very clear and knowledgeable Show details

Queensland Country Health Fund
Queensland Country Health Fund is excellent value. They have a very friendly team who offer exceptional customer service! Show details

see-u by HBF
I would like to acknowledge Alina for her stand out assistance she gave me with my recent claim form, my name is Reen and I’m 70 yrs old. With… Read more
following her instructions and her amazing patience with my little knowledge I have with navigating on my apple phone , she talked me through it in different ways to approach the problems and never gave up till it was completed. Her friendly manner and professionalism could not go unnoticed . I am very pleased to be a member of See-u

Westfund Health Insurance
I have been a Westfund member for 18 years. Living in a semi regional area. I love how westfund has some scheduled providers in those areas that… Read more
don't charge a gap. John Flynn hospital, Goldcoast and Southern Highlands Hospital Bowral are two of these which i have both used and had no gap on my admission. Its easy to use my phone to make claims. When there is a problem or question I have always had someone to talk too.

Australian Unity Health Insurance
- See all


When I signed up for my parents health insurance, they were happy to start taking my money, when I wanted to cancel, they did not cancel over the phone, had to send numerous email, they wanted more information, Show details

Allianz Care
- See all


Thanks Monica! For your prompt response to get my OSHC. Show details

TUH Health Fund
- See all


Professional, knowledgeable and courteous staff. Each time I have engaged with them my queries have been resolved promptly and efficiently. Highly recommended!! Show details

Nurses & Midwives Health

- See all


I spoke to Jen she was extremely helpful even found out there were things i have access to i didn't know. I recommend NMW to everyone i meet, in 50 years it is the best and easiest health fund we have been in. Show details

Peoplecare Health Insurance
I have been with Peoplecare for around a year and can say that their service and ease of which claims can be made is second to none. Also each time… Read more
I needed to speak to someone, there was no waiting on the phone and my queries/questions were answered and clearly explained. My recent to visit to hospital was also handled efficiently and promptly with no dramas. A staff member phoned me prior to going into hospital and clearly explained the ins and outs of what I could and couldn't do with my hospital cover. So happy with Peoplecare and thoroughly recommend them.

Frank Health Insurance
I live in a rural area with no mobile phone coverage. Frank then decides that because I have no mobile coverage I should no longer have access to my account details online. If you abuse me I don't deal with you. Show details

GMHBA Health Insurance
- See all


Member since 1962 aged about 21. Never considered changing Your phone response/staff are wonderful - thankyou Show details

ItsMy Health Insurance
I would like to take a moment to express my sincere appreciation for Nicolas from HCF and the exceptional service he provided to me. Over the years,… Read more
I have been approached by many telemarketers offering to compare my existing health insurance with other providers. Unfortunately, I often found that these conversations felt more like sales calls than genuine conversations. I never felt that someone was truly taking the time to understand my circumstances, listen to my concerns, or explain my options in a way that made me feel comfortable.
Then I spoke with Nick. Nick was genuinely one of a kind. In my eyes, he is a true legend. From the very beginning, he was polite, patient, caring and incredibly professional. Most importantly, he made me feel heard. He took the time to explain everything clearly, answer my questions and make sure I understood my options without ever making me feel pressured.
I had been with my previous health fund since 2009 approximately 17 years, and had never changed providers. I stayed with them for so long because I honestly believed there was probably nobody out there who could offer me something better or, more importantly, provide the level of service I was looking for.
Over time, I felt that my previous health fund was no longer meeting my needs. I had reached out to them numerous times over the course of a year, but I didn't feel that my concerns were being properly addressed or that I was receiving the level of care and attention I needed as a long standing customer.
I had almost given up on the idea of changing health funds altogether. Then Nick came along. What stood out to me most was his patience and persistence. He never gave up trying to find a suitable time to speak with me. He continued to communicate with me and email me options that worked around my availability, without making me feel pressured or rushed into making a decision.
His knowledge, professionalism and genuine care ultimately won me over. I am very glad that I made the decision to join HCF. In all honesty, it felt like a weight had been lifted from my shoulders. I finally felt that someone was actually listening to me and helping me find a health insurance option that better suited my needs.
I can honestly say that I probably would never have left my previous health fund if it wasn't for Nick. That is how much of an impression he made on me. Nick is a wonderful representative of HCF. His kindness, patience, professionalism and genuine approach to helping people should be recognised and appreciated. In a world where customer service can sometimes feel rushed or impersonal, Nick reminded me how much difference one caring and dedicated person can make.
Thank you, Nick, for taking the time to listen, explain, follow up and, most importantly, care. You didn't simply help me change health funds, You restored my confidence that there are still people who genuinely care about helping others.
HCF is very fortunate to have someone like you representing the organisation.

Police Health
- See all


I was in Police Health back in the 1990's but a marriage change and I was in BUPA for 20 years but now have rejoined and I'm extremely happy with their policy and service and very happy to be back. Show details

ahm Health Insurance

- See all


I really appreciate the assistance I received from Lee Gamble. She made the experience of becoming a new member very personable and is a great representation the AHM brand. Would absolutely recommend this service. Show details

Defence Health Health Insurance
Excellent thank you. Cover is costly but well worth it. Show details

HBF Health Insurance

- See all


I received very good service from HBF staff. I have been with them on and off since 1968. ( different surnames) Show details

Health Partners
Excelent service delivery and quality of work by all involved - Many thanks to all at Health Partners Show details

Doctors' Health Fund
This company is a disgrace. I have been a member now for many years and I am paying nearly $10,000 a year in premiums. I rarely make claims but… Read more
recently I had a hospital admission and submitted my claims soon after. These people give me the runaround constantly. They blame Medicare, Medicare blames them and then they both blame the provider and the only person that suffers me. I’ve spent over two hours on the phone with them in the past week and each time someone has given me a different answer or reason to why my claim is being held up. They make dreadful errors at my expense and when you email them to try to find out what’s going on, they either ignore you or respond with a single line and you are no better informed than you were previously. I will be getting out of this health fund as soon as I possibly can. Please think very carefully before joining them because if you need to make a claim, they will not pay it and they will make mistake after mistake and you will be chasing your tail for months on end until you finally give up because they wear you down. I outlaid $36,900 for a procedure and so far I have received $900 back. I pay top hospital cover. That is an absolute disgrace.

HCF Health Insurance
- See all


Had several issues while moving from BUPA to HCF with great promises. Had to call many times to resolve. this was with regards to coverage we had in… Read more
BUPA was not properly transferred to HCF.
Now the latest is our dentist has been removed from HCF panel for no reason even though the dentist agreed to their fee structure. JC Dental Como has been our dentist for a long time. The reason was HCF decided to reduce the number of dentists in the panel in that area. Not happy at all.

Union Health
You can tailor your health insurance to what suits you and your family. Consultants are knowledgeable and helpful. Prices are better than other providers. Show details

HIF (Health Insurance Fund)
To What if ….. I appreciate Hif as a health fund but I am over companies who don’t notify you when they are changing their systems : after failing… Read more
to be able to use my card and paying in full , I have had two 30+ minute phone calls about not being able to update my app info and having to use a downloaded claim form that I submitted only to have to call again - as I was asked what I wanted to happen next …. Only to learn that my claim Had not landed despite getting the automated response … hoping a more direct. Email provided will help … going to Physio again ( great by the way) . Tomorrow … what would happen if I did not have funds to pay?? When I have just paid a years “ enrolment “ !! ….
- review of above : great response from consumer help but still unable to get app up and running after another hour on the phone and no capacity to know when sorted but card worked at Physio - But warning: no matter what they say initially if you have to receive a code on your phone finally as can’t use your phone to register you need TWO devices for task completion. However they say they’ll send me $100 gift card but it won’t get back practice I missed and cannot make up! And I’d prefer the latter! This kind of issue is going on at Telstras new security version. . Not the fault of the person I spoke to At Hif who halve to answer the call . They were always trying to help …

Please inform call staff about time frames

Health Care Insurance
Great service and easy to use insurance – Pretty happy with HCI. Easy to use app and always been easy to get through to them over the phone. Great service and they go out of their way to help you. Show details

St. Lukes Health
Health Fund Down twice in two weeks when providers go to process a claim. Yes, I can go each time and claim in person at my nearest location in the… Read more
city. Why not claim online? It's not user-friendly, and if you make one error, it's endless emails or letters in the mail back and forth. I suggest they inject more money into tech updates; that would improve client wellness and make a heathier stress free island.

Latrobe Health Services
I have been a customer for over 12 years, I was on an old Gold Cover Policy, I called today, spoke with Kerry and she was absolutely fantastic. Great… Read more
Customer Service skills, very nice, helpful and professional. She found a cheaper Policy that fits my age & needs perfectly and save me $ 30 fortnightly. I was happy she provided me with the support I required and avoided me from moving to a different insurance company, she even offered to do a follow up with me in a week. I am delighted to have Kerry on the phone when I made the call, I definitely give Kerry a 5 stars.

Medibank Health Insurance
- See all


EVER TRIED TO TALK (=SPEAK IN WORDS) WITH MEDIBANK private? I tried 3 media (phone, screen and app) to try to make a claim for the SERVICE "Bone… Read more
Mineral densitometry". All the AI robots failed and just looked blank and the telephone voices kept passing me around because they didn't comprehend.
I mean there are a lot of ageing people with bone density problems.. Surely , a medical insurance company has heard of it? Do they refund a claim for that or NOT? aaaHHH DA!
Not the AI robots on the Medibank private app site or the web site. They therefore have not trained their HUMAN underlings how to handle such conversations as you wile-away an hour listening to their Toadyverts telling you to talk to a robot. I might as well talk to my Triffid mate here .

Hello and thank you for taking the time to share your… Read more

Navy Health
I was recently diagnosed as pre-diabetic and high cholesterol and my doctor put me on a preventative drug regimen to try to address it before it… Read more
became a health issue. Navy health refused my claims even though I had not claimed any of my pharmaceutical benefit previously. Not only that they refused to respond to me personally even though both my husband and I are ex-navy and listed on the policy. Don’t bother with them you can get better service and more flexible premiums elsewhere.

Hi Sam, Thank you for your feedback. We're sorry to… Read more

NIB Health Insurance
- See all


I’m only giving one star because I have to give something. I can’t believe that Nib have an agreement yo pay 60% back on my extras are now changing… Read more
the rules of existing long time customers that if I don’t go to one of their providers I won’t get my 60% back. That’s just rude. I have to ask my long term Physio & dentist if they are a nib preferred provider & if not I have to stop seeing them or get less back each visit. Wow. Thanks nib. I think it’s time to move on & I definitely won’t be recommending them to anyone.
RT Health Insurance 🏆 2026
5.0Award Winning, Affordable, Not-For-Profit Health Insurance.
Private health insurance in Australia
When you first take out private health insurance, you will need to decide if you require one or a combination of the following options:
If you don’t want any of them, you’re still covered for public hospital visits and basic checkups under Medicare, the Australian public healthcare system.
Getting private health insurance does not mean you give up your Medicare coverage; you can have both at the same time. Under Medicare, you can visit a public hospital as a public patient, but may be placed on a waitlist and cannot select your own doctor.
Medicare also covers your visit to a GP and most of the Medicare Benefits Schedule (MBS) fee for visiting a specialist, so if all you need are basic checkups, you may be fine relying on Medicare alone.
If you do decide to take up private health insurance, remember that you’re entitled to the same cover at the same price as anyone else, regardless of your risk profile. At the same time, if you're going to take out health insurance, it's important to choose a type that you actually use and aren't wasting money on. We go through the different types below.
Hospital cover
Private hospital cover is designed to take the strain off the public health system. To encourage people to join and spread the load across both systems, the government has several financial incentives for people to join a private health insurance fund.
If you’re interested in the financial benefits of private health insurance, or what rebates are available, you can read our article on the tax benefits of private health insurance.
Do I need hospital cover?
With hospital cover, you'll have peace of mind should any medical emergency or illness arise. You could otherwise be out of pocket for thousands of dollars or be put on a long waitlist for surgery.
Here are a few other reasons to take up private hospital cover:
- You get to choose your own doctor in either a private or public hospital.
- If you decide to go to a private hospital, you can choose from any that your provider has an agreement with.
- You have a higher chance of getting a private room when you go to a public hospital as a private patient.
- You may have reduced waiting times for some hospital procedures, such as elective surgery.
- Additional MBS fees and other costs may be covered as part of your policy.
- You can avoid paying the Medicare Levy Surcharge, which applies if you earn over $90,000 per year, or over $180,000 for families.
- You can avoid paying Lifetime Health Cover loading, which applies if you haven't taken hospital cover by the time you're 31.
If you have no problems admitting as a public patient to a public hospital should the need arise, then you may decide you don’t need private hospital cover. If the costs you incur during an unexpected hospital visit are less than the amount you would have spent on hospital cover up until that point, then you could finish out ahead without hospital insurance.
Unfortunately, there’s no way to tell if this will be the case, so many people take out hospital cover just for ‘peace of mind’, especially as they get older and the chances of needing it become more likely.
Here are some reasons to not get private hospital cover:
- Australia's public hospital system is generally good for those needing emergency surgery.
- The premium of your health insurance (which is what you pay for your policy) can be expensive, and unaffordable for many people.
- You may end up in a public hospital anyway for more complex medical conditions or treatments, as public hospitals usually have a wider range of medical equipment.
- You may pay more out of pocket for certain doctors, as private patients are often charged more than public patients, and your health insurance will probably only cover part of the cost.
Tiers of hospital cover
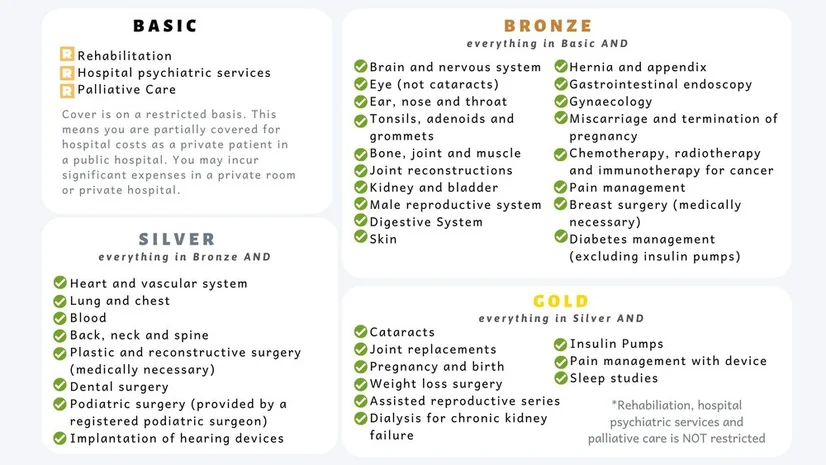
The tier system applies only to Hospital Cover and began rolling out in April 2019, becoming mandatory on April 1st 2020. It was designed to make comparison between providers more straightforward by dividing levels of cover into four tiers:
- Basic
- Bronze
- Silver
- Gold
Each of these tiers has its own minimum requirements that must be met in order for a policy to be classified as being part of that tier. These minimum requirements are cumulative, meaning that each increasing tier includes all the minimums of the tiers below it.
This graphic shows the minimal coverage requirements for each tier:
'Plus' policies
There is some wiggle room allowing providers to include additional coverage on top of the minimum requirements for a tier - these are referred to as ‘Plus’ policies. If an insurer offers a policy that provides cover that's above the minimum requirements of a tier, then they can advertise the policy as Basic Plus (+), Bronze Plus (+), or Silver Plus (+). Because a Gold policy covers everything, there’s nothing additional that can be added to it in order to make a ‘Plus’ version.
For example, surgery to remove wisdom teeth is covered under Dental Surgery, which is mandatory for Silver cover, but not Bronze. However, a provider may choose to include it on top of their normal Bronze policy to create a Bronze Plus policy.
This means you can claim this benefit without the full price increase that would come with an upgrade to Silver. This allows you to avoid paying for other mandatory benefits covered under Silver that you might never use, such as podiatric surgery.
It’s important to note that not all ‘Plus’ versions of the same tier are directly comparable, since each provider may choose to include different clinical categories as optional inclusions. For example, Provider A may offer a Bronze Plus package that includes bloodwork, while Provider B offers a Bronze Plus package that includes reconstructive surgery instead - they are both still Bronze Plus policies.
Extras cover
Extras insurance will help cover the cost of ancillary health needs, like dental care, clinical therapies and prescription glasses or contact lenses. If you don't use these services, you may prefer not to purchase Extras Cover as there is no tax benefit to having it.
If you're after just the basics and don't require more expensive treatments like orthodontics, you'll be able to extract the most value out of an entry-level policy. However, don't expect to get 100% back on your bills; most funds offer a 50-60% rebate.
Do I need extras cover?
There’s more value to be had from Extras Cover when you're using your extras regularly, so assessing your present and potential future needs is the best place to start.
Many providers won’t include extras cover for pre-existing conditions, so if you have a family history of a condition like osteoporosis or diabetes, you may need to be covered before these issues arise so that they’re not counted as a pre-existing condition.
Providers approach extras insurance in different ways. Some will give you a lot of flexibility over which services you want to include, while others have strict packages you must choose from.
If you start by writing down a list of your personal must-haves (e.g. complex dental, physiotherapy, and hearing aids) you can then whittle down the list of possible policies to only those that include exactly what you’re looking for.
If you're getting cover for your family or if you're aged between 55 to 79, then there are some perks to getting extras insurance:
- Families pay the same premium as couples, so children are covered for free. However, children under 5 on average typically get less than $100 in benefits each year, while children between 10 and $14 typically get almost $400.
- People aged 55 to 79 tend to get more use of extras insurance benefits than other age groups, and typically receive an average benefit of over $600 a year.
Dental cover
One of the most popular reasons to take out extras is dental cover. Dental is typically split into different levels of cover from routine or general up to major and complex procedures, with orthodontics usually being a separate option as well.
Additionally, depending on what procedures you have done and where, not everything may be covered under your Extras policy. For example, if you elect to have wisdom teeth taken out in a hospital, some of the hospital and doctor fees may not be covered under your Extras policy and you’ll have to pay these out-of-pocket.
Combined cover
Combined cover is hospital cover and extras cover combined in a single policy. Private hospital and extras insurance are different types of insurance, and you don't necessarily need both. Often, you can get a better deal by buying extras and hospital cover from two separate health funds.
Some people like the convenience of having to only deal with one health fund for both insurance types. Before you take out combined cover, think about whether you need both hospital and extras insurance.
Ambulance cover
Ambulance cover is the most basic type of cover, and covers the cost of an ambulance in an emergency.
Unless you live in Queensland or Tasmania, ambulance call-out fees are not covered under Medicare and will have to be paid for out-of-pocket. You can find out more about ambulance fees for your state in our ambulance cover article.
When shopping around, check with an insurer to see what kind of ambulance cover they offer. Some only offer ground transport in an emergency and will not offer air ambulance. Some might just cover emergency ambulance and exclude transport to transfer patients between hospitals.
What to consider when choosing health insurance
Once you've decided what level of cover is right for you, you can start comparing different providers and policies. Each policy will have a product disclosure stateent (PDS) - read these to understand the inclusions and exclusions.
Here are some more things to consider when choosing health insurance.
Your personal circumstances
What's going on in your life will usually have a significant impact on which type and level of cover will best suit you.
Consider the following questions:
- Do you have any pre-existing conditions that may require medical treatment in the near future?
- Are there any hereditary health conditions in your family that could have an impact on you?
- Are you planning on starting or growing a family and will you require obstetrics cover?
- Do you need cover for partners or dependants?
- How will your health needs and requirements change as you get older?
You should be honest about your health history when you take out a policy. Your insurer may not pay your claim if they believe that you have misled them.
Premiums
Generally, the higher your premium, the more benefits you can claim. You can usually tweak your health insurance policy to make your premium more affordable. Consider doing the following:
- Customise your excess. Choosing a higher excess (what you agree to pay towards a Hospital claim) will usually reduce your premiums.
- Choose a co-payment. This is a fee that you agree to pay for each day you're a patient in a hospital. It could be a more affordable option if your co-payment is less than what the excess would be and if you know how long you'll need to stay in hospital.
Waiting periods
Most health funds have a waiting period before you're able to claim on any services. The length of the waiting period usually depends on the type and complexity of the medical treatment.
- For hospital cover, waiting periods for pre-existing conditions or obstetrics (pregnancy) are usually 12 months.
- Waiting periods for extras vary; it can be 2 months for many services, and is usually 12 months for major dental treatment.
- Waiting periods typically won't apply if you're switching policies or health funds to a similar level of cover.
Decision time
One thing to remember that will help you avoid confusion when browsing policies is that hospital cover is sorted into Basic / Bronze / Silver / Gold tiers, while extras will be called whatever marketing name the provider has come up with for themselves (e.g. 'Lifestyle Extras,' 'Black Extras 60,' 'Essential Extras,' or 'Top Extras.')
It may be possible to mix-and-match your hospital and extras cover in many ways, such as combining the most expensive hospital cover with the most basic extras cover or vice-versa. Your provider may also offer some pre-selected hospital & extras combinations.
ProductReview.com.au is a great tool for seeing feedback about Health Insurance providers from real customers. You can browse our list of health insurance providers and easily see a summary of how other Australians rate their health fund for customer service, value for money, and transparency.
If you click through to an individual fund, you can use the Filter Reviews button to narrow down the reviews to see just those that are similar to you, or that you might be interested in reading.
Remember: insurance isn't forever. Reassess your policy regularly to ensure that it's meeting your needs and you're making the most of it.
This article is part of our series on private health insurance.
Disclaimer: The information on this website is for general information only. It should not be taken as constituting professional advice from the website owner - ProductReview.com.au. ProductReview.com.au is not a financial adviser. You should consider seeking independent legal, financial, taxation or other advice to check how the website information relates to your unique circumstances. ProductReview.com.au is not liable for any loss caused, whether due to negligence or otherwise arising from the use of, or reliance on, the information provided directly or indirectly, by use of this website.
Hi Shashank, thanks for sharing your feedback.… Read more